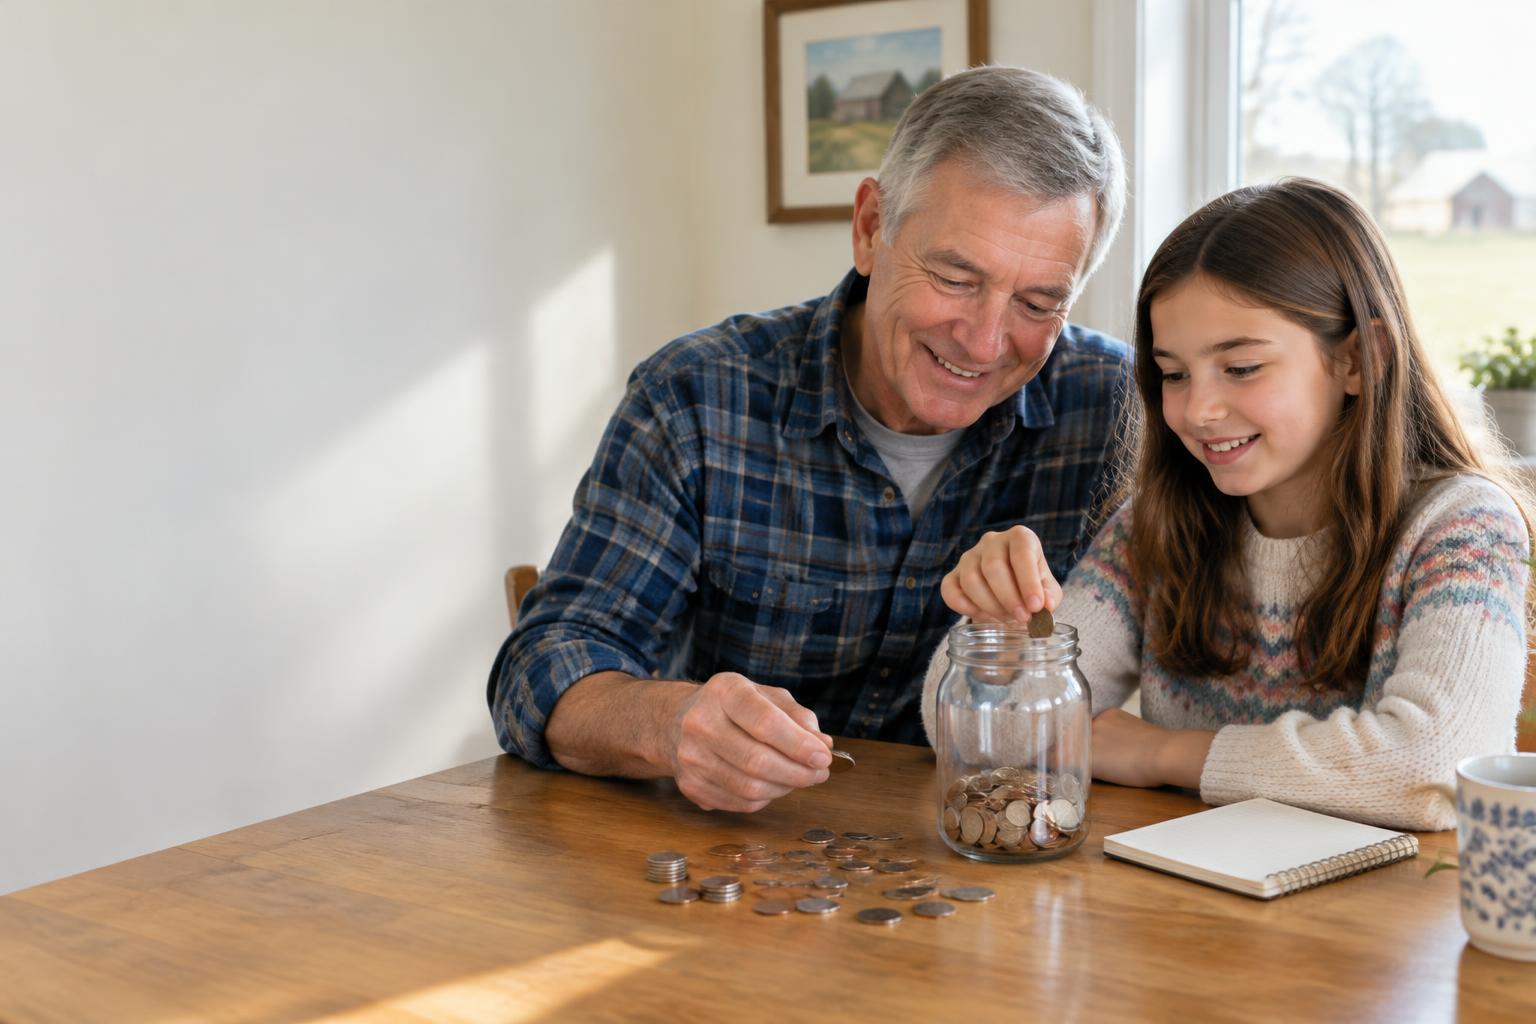
iRoth4U / A LEGACY THAT STARTS WITH A LESSON
Reasons to start a Roth IRA.
Grandparents: plant a habit, not just a dollar.
Imagine sitting beside your grandchild after their first paycheck: “What could this little beginning make possible?” Start with saving. Explore a custodial Roth IRA when earned income makes them eligible.
Start with the grandkidsFree education. Real eligibility rules. Future possibilities—not promised returns.
THE FIRST FENCE POST
A custodial Roth IRA starts with the child’s work—not the grandparent’s gift.
For a minor with eligible compensation, a custodial Roth IRA can connect today’s work to a distant retirement horizon. Your greatest contribution may be the lesson: earn, save, understand what you own, and give time a chance to work.
Sit down together.
Ask what matters to them. Compare something they want soon with something worth building over time. Keep near-term savings separate from retirement investing.
Make a family savings pact.
Consider matching a portion of eligible earnings. For example, $600 of eligible compensation could support up to $600 of IRA contributions from all sources, if all other requirements are met—not $600 from the child plus another $600 from you.
If there’s no earned income yet, teach anyway.
Use a savings jar, a bank savings account, or a simple spending-and-saving notebook. There is no need to manufacture wages or rush into a retirement account to teach a good habit.
Know which account you’re opening.
Robinhood’s support page, checked October 11, 2026, says it does not currently support custodial IRAs, including custodial Roth IRAs. Its custodial brokerage account is a taxable UTMA account—not a Roth IRA. For a child’s Roth, compare providers that specifically offer custodial Roth IRAs and confirm their requirements.
Check Robinhood’s custodial-account FAQTROUBLESHOOTING 101: CHECK YOUR SOURCES FIRST
Six gates to check before contributing.
01
The child needs their own eligible compensation.
Wages and qualifying net self-employment income can support contributions. A birthday gift, investment income, or an ordinary allowance is not earned compensation. Being young—or owing no federal income tax—does not by itself prevent eligibility.
02
Your gift can fund the contribution. It cannot create eligibility.
A grandparent may supply the cash, but the child’s total traditional and Roth IRA contributions still cannot exceed their eligible compensation or the applicable tax-year limit, whichever is lower. Direct Roth income restrictions also apply. Coordinate with parents and any other contributors.
03
Real work needs real records.
Keep W-2s or a record of actual services, dates, customers, payments, and expenses. Do not relabel an allowance as wages or invent a job. Family employment, self-employment, filing obligations, and the net compensation calculation deserve a tax professional’s review.
04
The money belongs to the grandchild.
An adult custodian manages the minor’s account under the provider’s rules. It is not the grandparent’s retirement money. Confirm who may act as custodian and when control passes to the child under the account agreement and applicable state law.
05
Funding an account is not investing it.
Compare providers that actually offer custodial Roth IRAs, including fees, investment choices, and minimums. Choose investments suited to the child’s horizon and risk. A Roth IRA is an account wrapper; its investments can lose value.
06
Retirement money has withdrawal rules.
Regular contributions generally come out first without federal income tax or penalty. Earnings are different: age-based qualified withdrawals generally need both age 59½ and the five-tax-year period. Some exceptions waive a penalty without making earnings tax-free. Check IRS Publication 590-B before withdrawing.
TROUBLESHOOTING 101 / FURTHER RESEARCHCheck your sources first.Every link below opens in a new tab, so iRoth4U stays right here with you.
- IRS Publication 590-A: compensation and contributions
- IRS: current annual limits
- IRS Publication 590-B: withdrawal rules
- IRS: Roth IRA overview
IRS publications are revised over time — the pages above carry the current rules.
SEE THE NUMBER. IMAGINE THE POSSIBILITIES. BUILD BACKWARD.
What do you want your freedom to make possible?
A Roth IRA is not just a retirement label. It can be one part of a plan for the life you want. These 36 ideas are aspirations—not special withdrawal exceptions or promises that a balance will cover them. Size the goal, protect essential retirement needs, then choose a sustainable saving habit.
Give the next generation a head start.
- Teach a grandchild to save from a first paycheck.
- Offer a family savings match within the child’s IRA eligibility.
- Help a young worker understand compounding.
- Build a tradition of talking honestly about money.
- Show a grandchild how to research before investing.
- Help your family distinguish a gift from earned income.
Choose how you spend your working years.
- Plan toward retirement at 59½.
- Work part-time because you want to—not because you must.
- Fund your own business after your Freedom Date.
- Build a creative second act.
- Make room for mentoring younger workers.
- Take a career break with a funded plan.
Make room for the adventures.
- Travel the world at your own pace.
- Take the grandchildren on a meaningful trip.
- See America one road trip at a time.
- Learn a language where it is spoken.
- Visit family without putting travel on credit.
- Build time for a long-awaited personal adventure.
Picture the place—and the rewards.
- Buy your dream home in cash, if the whole plan supports it.
- Buy the latest Corvette without sacrificing essential retirement needs.
- Renovate a home for your later years.
- Create a workshop, garden, or art studio.
- Make space for multigenerational family visits.
- Fund a hobby you have put off for years.
Support the people and causes you love.
- Help fund your grandchildren’s interests.
- Support music, sport, science, or art lessons.
- Help an adult child through a difficult season.
- Support a cause that reflects your values.
- Leave a legacy to your chosen beneficiaries.
- Give generously within a sustainable spending plan.
Build flexibility—not just a balance.
- Have qualified tax-free withdrawals as one retirement income option.
- Reduce reliance on taxable withdrawals when your plan allows.
- Keep assets growing without lifetime RMDs for the original Roth IRA owner.
- Plan around Medicare income surcharges with professional guidance.
- Balance spending today with tomorrow’s purchasing power.
- Give your future self more choices, not another guarantee.
Age 59½ is our planning anchor, not guaranteed retirement readiness. Qualified earnings withdrawals generally require age 59½ and the five-tax-year rule. Original Roth IRA owners have no lifetime required minimum distributions; beneficiaries have their own distribution rules. Qualified Roth withdrawals generally do not add to Medicare IRMAA income, but a taxable conversion can. Review large purchases, taxes, inflation, and investment risk with a qualified professional.
FREE LEARNING COMES FIRST
“Free to open” is not “free of every cost.”
Robinhood states it does not charge fees to open or maintain its investing account. Check its current IRA terms and fee schedule before choosing an account: fund expenses, regulatory fees, transfers, optional subscriptions, and other costs may apply. Contributions require your money, and investments can lose value. No paid course or signup is required to learn here.
Check Robinhood’s current fee informationThe optional Robinhood referral below is for readers independently considering its available accounts—not a link to open a custodial Roth IRA for a grandchild.
An optional thank-you for the trail.
If you independently decide Robinhood is right for you, using our referral link is one way to say thank you for the free tools we’re building. Learning comes first. Opening an account is your choice.
Referral disclosure: Dan Johnson may receive a reward if you sign up through this link and meet Robinhood’s qualifying requirements. Any reward is subject to Robinhood’s current offer terms; no credit, stock, fractional share, or reward amount is guaranteed.
Visit Robinhood — referral linkYou do not need to use this link, open an account, fund investments, or buy a subscription to access iRoth4U’s free tools or the linked learning articles. A Robinhood signup does not enroll you in an iRoth4U team. Education is not a recommendation to trade; investments can lose value.